A rental property investment is more than a building with a rent attached. Its performance depends on the people likely to rent it, its location and condition, the costs of ownership, the time it may sit vacant and the investor’s ability to manage risk. Compare multiple opportunities using conservative assumptions and independent checks.
Understand the likely tenant
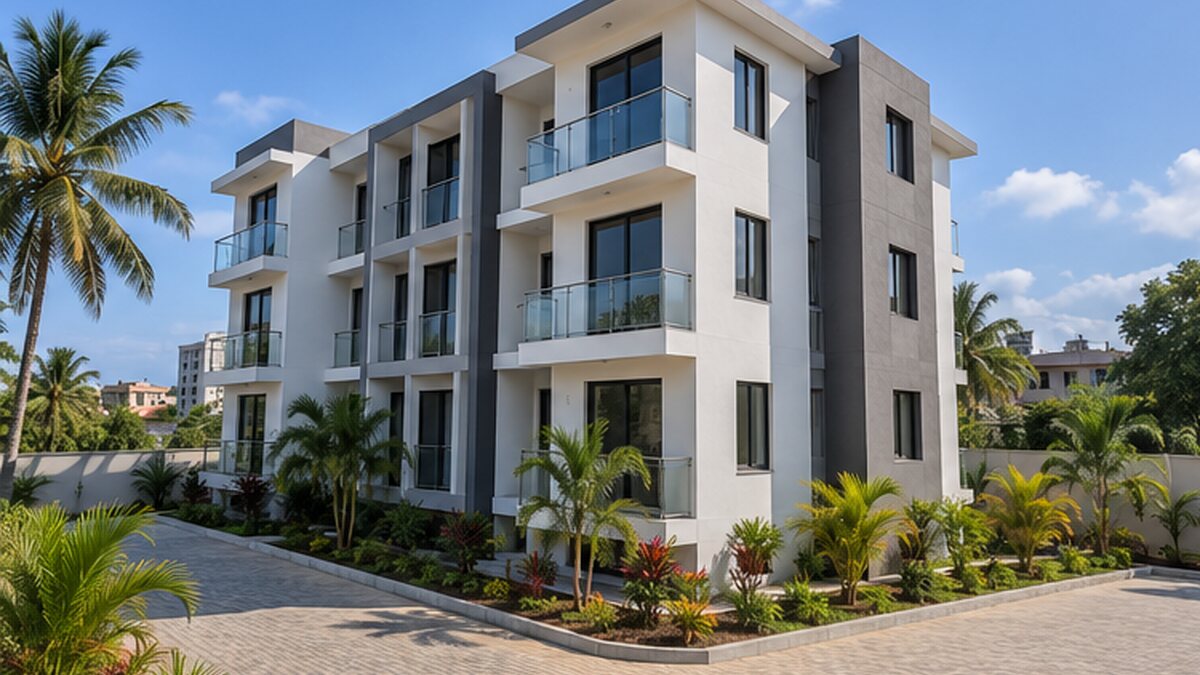
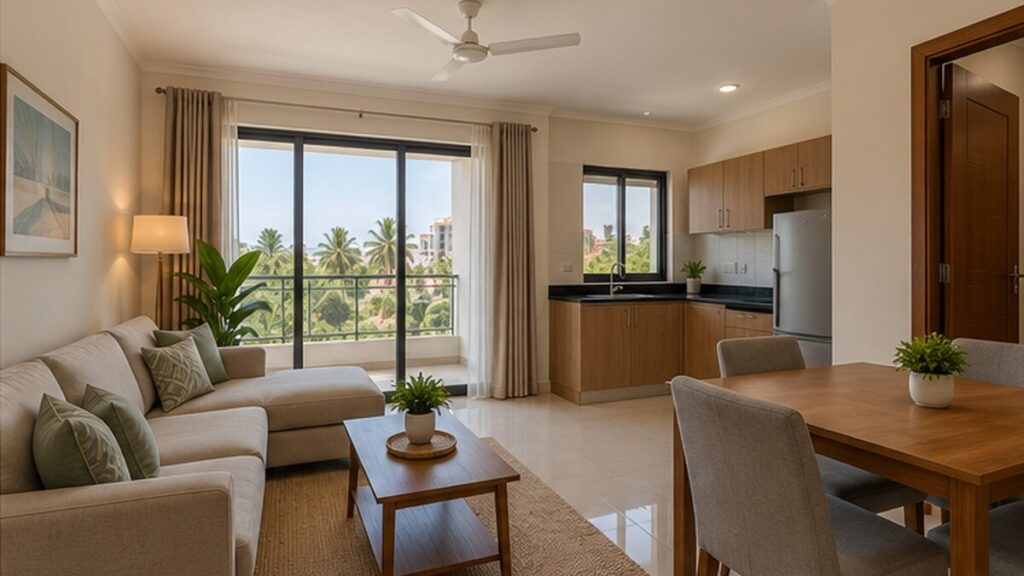
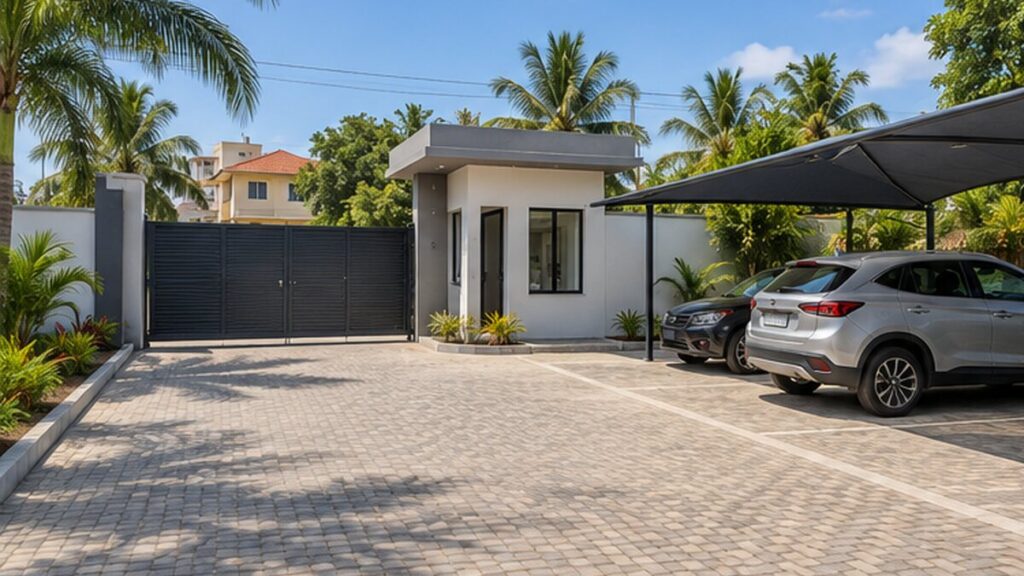
Start by describing the household or tenant most likely to choose the property. Consider the size and layout, transport access, nearby work or education, parking, security arrangements, storage and services. The goal is not to stereotype a neighbourhood but to test whether the home’s features fit a plausible tenant’s needs.
Look at current comparable rental listings and speak with people who understand the local area. Confirm how long similar properties appear to remain advertised, what is included in rent and whether the advertised details can be verified. Listings are evidence of asking rents, not proof of achieved rent or continuing demand.
Assess location and the property itself
Visit the area and the property at different times. Test road access and practical journeys. Check the building’s condition, water and power arrangements, ventilation, drainage, security and maintenance of shared spaces. Ask for records about repairs and service charges. Obtain a professional inspection if structural or technical condition could affect the decision.
Consider how easily the layout can be maintained and whether replacement parts or qualified repair services are accessible. A property with attractive finishes may still require expensive upkeep. Budget for routine painting, plumbing, appliances, exterior maintenance and occasional larger repairs rather than assuming every month will be cost-free.
Estimate income and costs separately
Begin with an achievable annual rent estimate based on comparable homes, then allow for periods without a tenant and possible delayed payments. List all costs: maintenance, insurance if applicable, management, utilities paid by the owner, shared building expenses, taxes or levies that apply, advertising, professional fees and financing costs. Confirm tax treatment and obligations with an appropriate Tanzanian tax professional.
Hypothetical gross-yield example: If a property costs TZS 200,000,000 and the hypothetical rent is TZS 1,000,000 each month, annual rent would be TZS 12,000,000. Gross rental yield would be (12,000,000 ÷ 200,000,000) × 100 = 6%. These invented figures are only to demonstrate the formula. Gross yield excludes vacancies and every operating or financing cost; it is not a forecast or guarantee of return.
To understand net cash flow, subtract realistic expenses from rent received and account for the timing of those expenses. If you use a loan, include actual repayment terms supplied by the lender. Do not substitute a generic interest assumption or an optimistic rent estimate for verified numbers.
Consider liquidity and downside risks
Property can take time and expense to sell. Ask yourself how you would manage if the unit were vacant for several months, a major repair arrived unexpectedly or your income changed. Keep an accessible reserve appropriate to your circumstances. Avoid investing money you may need quickly for essential commitments.
Check ownership and transaction documentation, permitted use, access, services and any restrictions with qualified professionals. Review the lease process and think through tenant screening, payment records, repairs and dispute resolution. A potentially attractive rent does not compensate for unresolved title or boundary questions.
Compare opportunities on the same basis
- Use a conservative rent estimate supported by current comparisons.
- Record vacancy, repairs, management, taxes and shared costs separately.
- Inspect the property and verify title, use and access.
- Check whether the likely tenant would value the home’s real features.
- Stress-test the budget against lower rent and higher repair costs.
Decide what evidence would change your mind
Before viewing, write down the rent level, vacancy allowance, repair reserve and maximum total purchase cost you are willing to use. Identify conditions that would make you stop: unclear ownership, access that cannot be confirmed, a repair estimate outside your capacity, or rental demand supported only by a seller’s claim. This simple discipline helps you assess an opportunity on evidence rather than momentum.
Consider how the investment fits alongside your other savings and obligations. A property may be difficult to sell quickly, and rental income can vary. Avoid concentrating money you may need for emergencies into an asset whose sale timing is uncertain. A qualified adviser can help assess the risks for your own financial situation.
A good investment is one whose verified characteristics and realistic cash flow match your objectives and risk tolerance. Compare several properties before committing, and seek qualified legal, valuation, tax and financial advice for the specific transaction.
Before making an offer, prepare a property-specific due-diligence list. Confirm the ownership interest and boundaries, the permitted use, access, utility arrangements, building condition, service charges and any tenancy already in place. Ask who holds keys, which fixtures transfer and what repairs are planned. A clean rental projection is not useful if it assumes a property can be legally or practically used in a way the records do not support.
Finally, decide who will handle enquiries, viewings, screening, rent records and repair coordination. If you intend to manage the home yourself, include the time and travel involved. If you expect to appoint a manager, obtain actual terms and include the cost. These operational choices affect both the cash calculation and the type of property that will suit you.
Add comment